Privacy Experts Warn of Surveillance Risks from Address Linking
Starting 1 January 2026, UK cryptocurrency exchanges will be required to collect and report users' home addresses under new tax rules aligned with the OECD's crypto asset reporting framework. The changes, introduced by HMRC, aim to improve tax compliance but have raised alarms among privacy advocates who warn that linking personal addresses to public blockchain transactions could expose Bitcoin users to security risks. Critics argue the move undermines the pseudonymous nature of cryptocurrency use and could create vulnerabilities if data is mishandled or breached.
Breaking news
 STRK Surges 25% as Starknet Votes on Ethereum 'Divorce' for Quantum Security
 Starknet Launches Community Vote on Independent L1 Research Direction
 XRP Whale Activity on Binance Reaches Seven-Month Peak
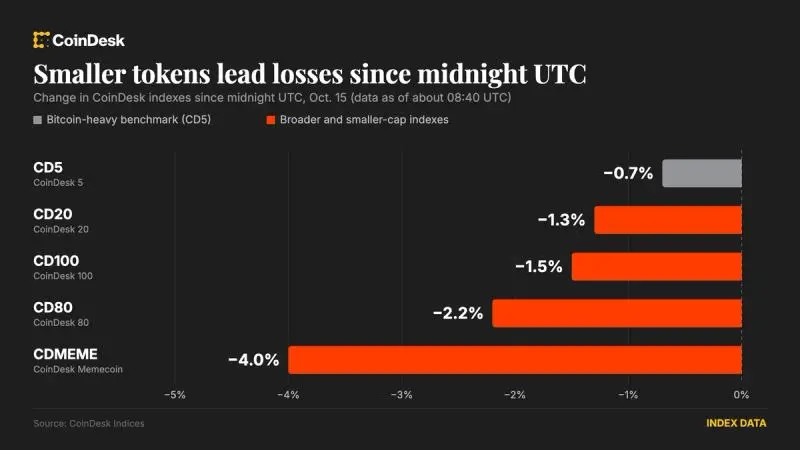 Bitcoin Holds Above $80,000 Amid Asian Market Turmoil
Privacy specialists caution that combining KYC-collected home addresses with publicly visible Bitcoin transaction data could enable detailed profiling of individuals. Once an address is tied to a blockchain transaction, analysts might trace spending habits, income levels, or associations with certain services. This level of exposure, they say, goes beyond standard financial oversight and resembles surveillance typically reserved for criminal investigations. The concern is amplified by the permanence of blockchain records, which cannot be altered or deleted once published.
How Might This Affect Everyday Crypto Users?
For regular users who buy, sell, or hold Bitcoin through UK-based exchanges, the rule means their residential information will be stored by platforms obligated to share it with tax authorities. While exchanges already collect identification for anti-money laundering purposes, the mandatory inclusion of home addresses represents a significant expansion of data gathering. Users concerned about doxxing, targeted attacks, or unintended data leaks may reconsider using regulated platforms, potentially pushing activity toward less transparent or offshore services that operate outside UK jurisdiction.
Will this rule apply to all cryptocurrency transactions? No, the reporting requirement applies specifically to crypto asset exchanges operating in the UK and covers transactions involving the exchange of crypto for fiat currency or other digital assets. Peer-to-peer transfers without intermediary platforms are not directly captured under this rule.
Frequently Asked Questions
Can users opt out of providing their home address? No, compliance with the OECD framework is mandatory for exchanges, and users must provide verified residential information to use regulated services. Refusal would likely result in account restrictions or closure under KYC and AML regulations.
What safeguards are in place to protect this data? HMRC states that data will be handled under existing UK tax information security protocols, though specific technical measures for safeguarding address data linked to blockchain activity have not been detailed. Exchanges remain responsible for securing user information under UK GDPR rules.