Why Banks Are Turning to Bitcoin
Banks across the globe are accelerating their adoption of Bitcoin, signaling the start of the cryptocurrency’s first institutional cycle. Industry insiders and analysts say that the surge is driven by a mix of regulatory clarity, growing institutional demand, and the fear of missing out (FOMO) among traditional financial players.
Breaking news
 Fast Confirmation Rule Cuts Ethereum Transfer Times to Seconds on Gnosis Bridge
 Decrypt and Myriad Launch Unified Wallet on Solana
 Astroport Discontinues Tokenholder Governance After Security Breach
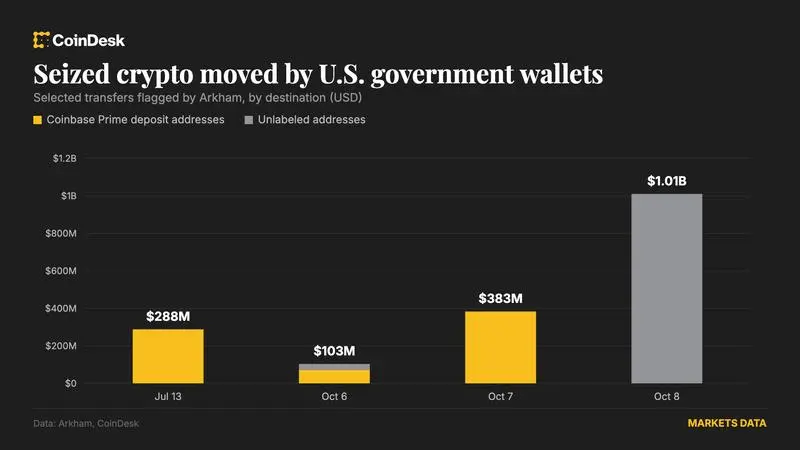 U.S. Government Shifts $1 Billion in Bitcoin From Bitfinex Hack Wallet
The shift began in earnest in early 2026, when several major banks announced pilot programs to offer Bitcoin custody and trading services to their clients. These moves followed a series of positive regulatory developments, including clearer guidance from the U. S. Securities and Exchange Commission and the European Union’s Markets in Crypto-Assets Regulation. As a result, institutional investors are now able to enter the market with greater confidence and lower risk.
Banks are attracted to Bitcoin for several reasons. First, the digital asset offers a new asset class that can diversify portfolios and provide a hedge against inflation. Second, Bitcoin’s limited supply of 21 million coins creates scarcity that can drive long‑term value appreciation. Finally, the technology behind Bitcoin—blockchain—offers transparency and security that traditional banking systems can leverage for cross‑border payments and settlement.
How Bitcoin Lending Is Changing the Landscape
According to Shawn Owen, CEO of SALT Lending, „FOMO is real. We see a growing number of institutional clients asking about Bitcoin exposure. They want to stay ahead of the curve and not miss out on what could become a core component of modern investment portfolios.” Owen also highlighted the role of institutional lending platforms that facilitate Bitcoin-backed loans, allowing banks to extend credit while holding digital collateral.
Bitcoin lending has emerged as a key driver of institutional interest. By borrowing against Bitcoin holdings, investors can unlock liquidity without selling their assets. This mechanism is particularly attractive during periods of market volatility, as it preserves exposure to potential upside while providing immediate cash flow.
SALT Lending’s platform offers competitive interest rates and robust risk management protocols. The company reports that its average loan-to-value ratio has increased by 15% since the beginning of 2026, reflecting growing confidence among borrowers. Moreover, the platform’s automated smart‑contract infrastructure reduces counterparty risk and improves settlement speed, making it an appealing solution for banks looking to integrate Bitcoin into their product suites.
Will the Institutional Cycle End Soon?
The question on many investors’ minds is whether this surge will be sustained or merely a short‑term trend. Analysts suggest that the institutional cycle will continue as long as regulatory frameworks remain supportive and the underlying technology proves reliable. However, market dynamics could shift if new competitors emerge or if macroeconomic conditions change significantly.
In the near term, banks are expected to expand their Bitcoin offerings, including custody, trading, and lending services. This expansion will likely lead to increased market liquidity and tighter price spreads. For retail investors, the institutional presence may bring greater stability to Bitcoin’s price and reduce volatility.
Frequently Asked Questions
What makes Bitcoin attractive to banks? Banks see Bitcoin as a new asset class that offers diversification, scarcity, and technological benefits such as blockchain transparency and security.
How does Bitcoin lending work for institutions? Institutions can borrow against their Bitcoin holdings using smart‑contract platforms, unlocking liquidity while retaining exposure to potential price gains.
Will the institutional interest in Bitcoin continue? As long as regulatory clarity persists and the technology remains robust, institutional interest is likely to grow, potentially leading to greater market stability and liquidity.